Investments employees want. The fiduciary advisor HR needs.
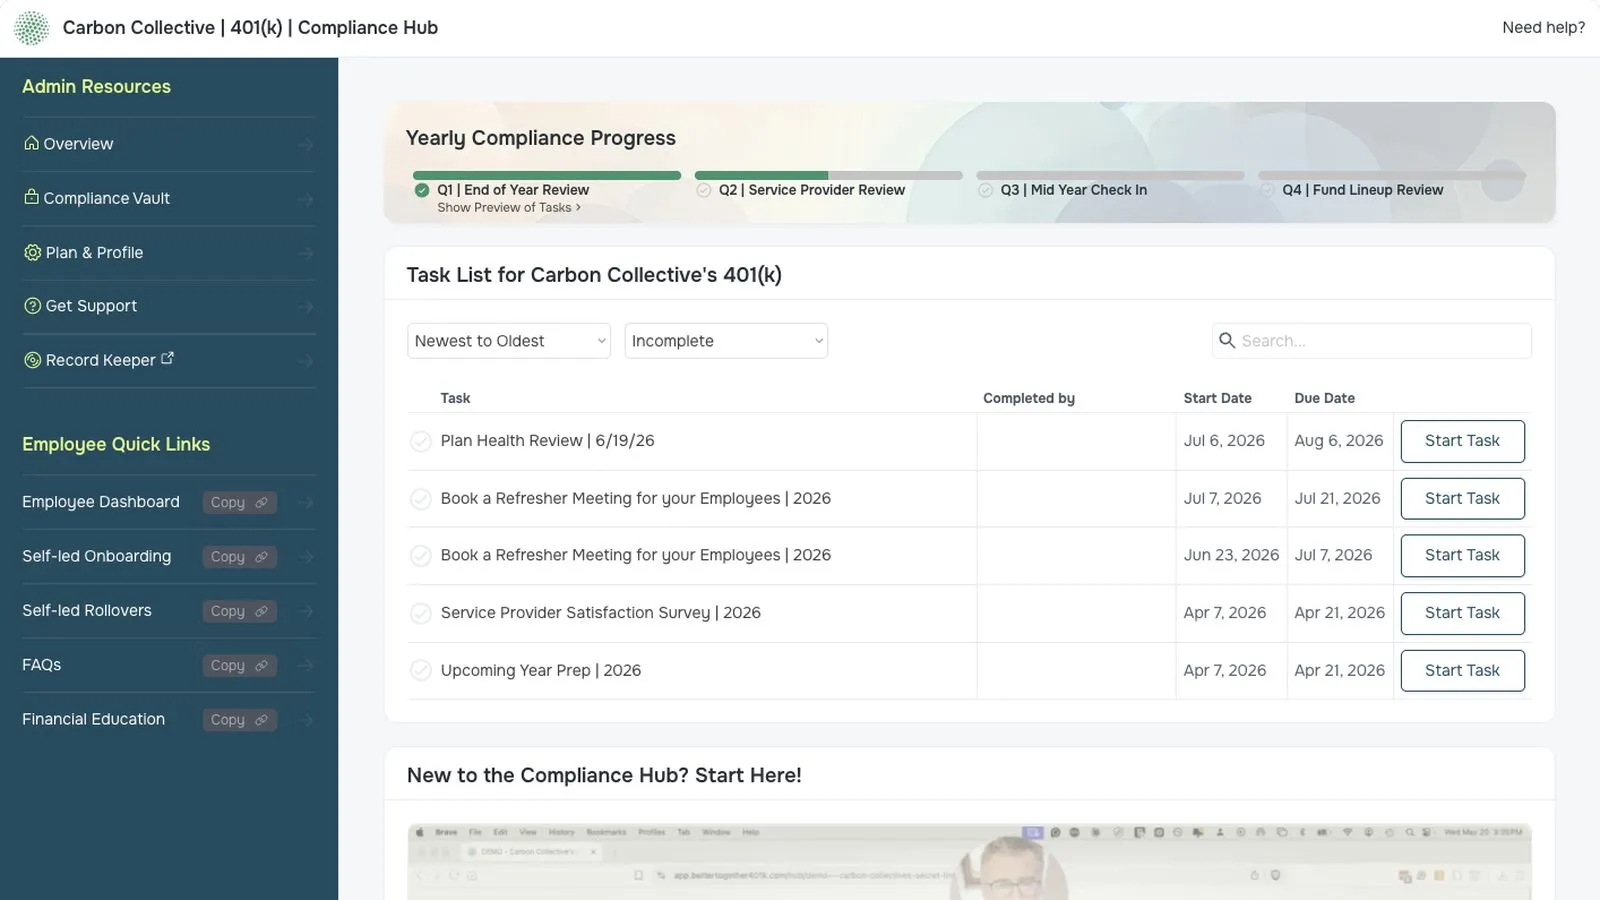
Employees get vetted funds and financial education. HR gets fiduciary guidance every step of the way.
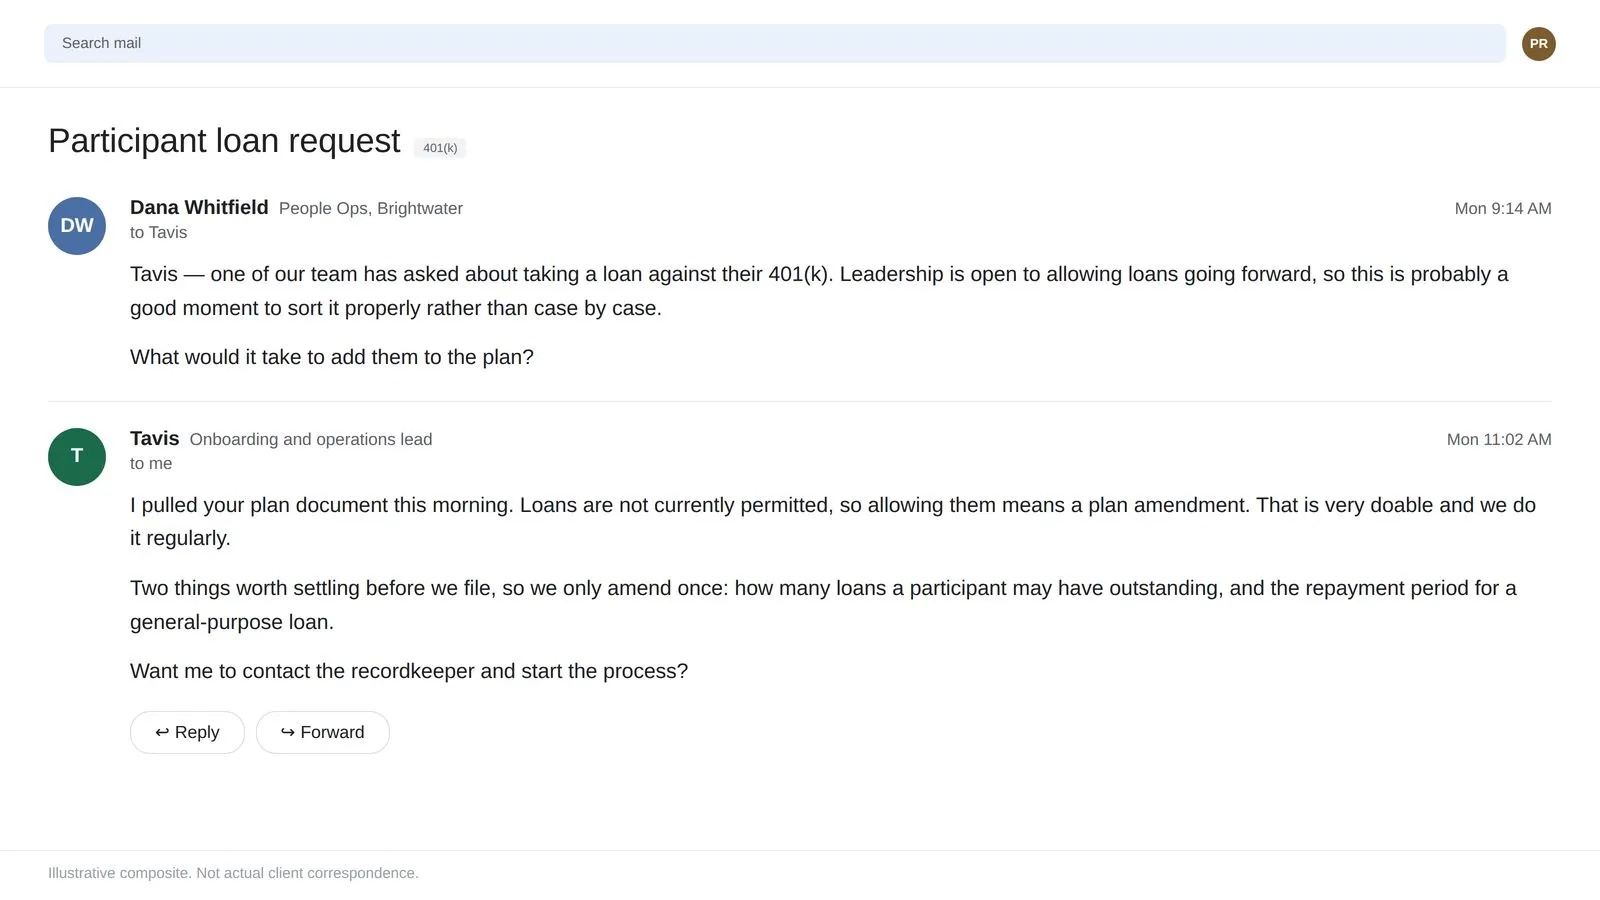
Illustrative composite. Not actual client correspondence.The messages shown are composites written to illustrate the kinds of questions clients bring us and how we answer them. They are not real correspondence and no client is identified. Response times shown are illustrative and are not a guarantee of future service levels.
We help nonprofits
Carbon Collective has been a win-win for us. Employees have more socially and environmentally responsible choices and … as administrators, we get responsive and friendly support, including helping us with our recordkeeper, for a lower price!
Deeply proud of the trustThese testimonials were provided by real, current clients with their explicit permission. Nobody was paid or compensated in any way for providing a testimonial, and we are not aware of any conflict of interest in their giving one. Testimonials are not a guarantee of future performance or success and may not be representative of the experience of other clients. we have earned from the 139Pension and profit sharing plans reported in Item 5.D.(1)(g) of our Form ADV Part 1A, annual amendment filed March 25, 2026. 401(k) and 403(b) plans we serve.
How we help.
Two jobs. Only one of them is in the contract.
Build and maintain your fund lineup, as your 3(38)A 3(38) investment manager takes discretion over the plan’s investment lineup and accepts, in writing, the fiduciary responsibility for selecting and monitoring it. The plan sponsor still has the duty to select and monitor the 3(38)..
We choose the funds, monitor them, and sign for those decisions. Your remaining duty is to monitor us.
Be the first person you ask, about anything.
A loan request. Hiring in a new state. Someone asking what a Roth is. You send it to us first.
Can we work with your plan?
Three questions. Your answers stay on screen.
Do you have a retirement plan today?
We can be added to most recordkeepers without moving your plan. If yours needs moving, we run the search and handle it.

Talk to Breene.
Twenty minutes, no deck. Tell me about your plan and I will tell you honestly whether we are a fit.
How we build fund lineups.
Your diverse team deserves diverse investment options.
What if they are missing major known trends like climate change?
Are markets properly pricing Environmental, Social and Governance-related risks?
One of these will perform the best over the coming decades.
Your job isn’t to read a crystal ball; it’s to give your team diversified options.
Diversification does not guarantee a profit or protect against loss. More on these three philosophiesPassive, Long Horizon and ESG describe three investment philosophies, not three levels of expected return. Each is offered so participants can choose the approach they prefer; none is recommended over the others, and inclusion of a fund in the lineup is not a recommendation to any individual participant. Investing involves risk, including possible loss of principal.
What you get for your fees.
Our pricing is simple. We try for 10% less than your current advisorIf your plan already works with a human advisor (people who build and monitor your fund lineup), we aim to price our advisory fee ten percent below what you currently pay them. Pricing is based on the complexity and size of the plan. As of September 18, 2026; this has been our practice for some time. It is not a comparison to bundled providers that charge an asset-based 3(38) fee, such as Guideline or Human Interest, which operate at a different level of service. For plans with no incumbent advisor we quote case by case: we would rather fees did not get in the way of a long partnership..
Send us your 408(b)(2).
We’ll benchmark your fees and send a competitive quote. One fiduciary to-do checked off your list.
- A plain-English breakdown of every fee in your current plan
- A side-by-side quote of your total plan cost, line by line
- Back in your inbox within a business week, no call required
Quotes reflect your plan’s size and complexity and are not a guarantee of lower fees. We compare your total plan cost, including advisory, recordkeeping and fund expenses, using your current 408(b)(2) disclosures. Recordkeeping and fund expenses are paid to third parties and shown as separate line items. See our Form ADV Part 2A for full fee details.
Questions plan sponsors ask
Short answers first.
If yours isn’t here,
ask Breene directly.
Usually answered in one to two business days, by whoever knows the answer.
Do I have to move my plan to work with Carbon Collective?
Probably not.
Most recordkeepers are moving to a full open-architecture platform, and we never like to move a plan if we don’t have to.
That said, we see a lot of dissatisfaction with recordkeepers. We love negotiating recordkeepers against each other, and we have several we like and have built strong working relationships with. So we often find that a recordkeeper move can mean lower fees for better service.
Do you work with small employers?
Yes. We serve plans of all sizes, from new startup plans to mature ones.
Sometimes, to make the math work on a new plan, we’ll add a monthly fixed fee so our costs are covered while the plan grows.
Can my team still invest in index funds like the S&P 500?
Of course. Our job is to increase the options your team has, not take them away.
We build and maintain a full fund lineup of best-in-class funds across asset classes for three investment philosophies: Passive, Long Horizon (climate-oriented) and ESG. Your team chooses whichever of those funds is right for them.
Is it safe to include ESG funds in our 401(k) or 403(b)?
Yes. The financial rationale for ESG investing is sound.
It argues that traditional stock traders focus too heavily on balance-sheet evaluations of companies and ignore knowable Environmental, Social and Governance-related risks and opportunities that can materially affect returns.
Where you run into potential fiduciary trouble is if such funds are included for non-financial reasons. Read that carefullyThis answer describes the fiduciary framework plan sponsors work within. It is not legal advice and is not a recommendation to include or exclude any fund. Plan fiduciaries should reach their own conclusions, in consultation with ERISA counsel, based on their plan’s facts.
How long does it take to get started?
It can take up to four months, depending on the state of your plan.
Adding us as the 3(38) on your existing recordkeeper can be immediate. It then takes around 45 days to process an updated fund lineup.
Launching a new plan generally takes about a month.
Moving a plan to a new recordkeeper generally takes around four months, because your old recordkeeper has 90 days to comply with the directive. They often take the full time, so they can maximize fees before you go.